
 Newsletter
 Shop
 Login
 Menü




 4/2026

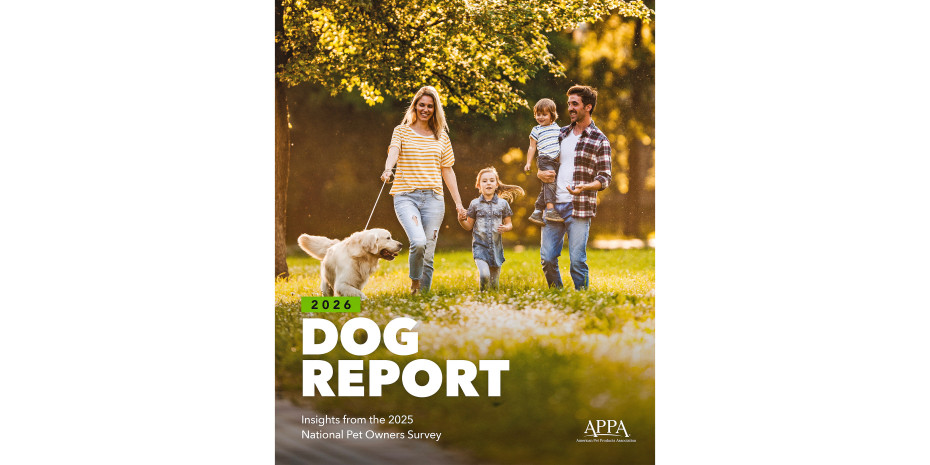
By 2025, dog owners were no longer prioritising spending as much as possible, but rather getting the best value for money. As the report details, this presents new challenges for manufacturers, retailers, and service providers, but also new opportunities.
Growth without a spending boom
The number of US households with dogs increased to 71 million by 2025. This represented a 4 per cent increase on the previous year. However, this growth in the number of dog owners was not accompanied by a proportional increase in spending. Instead, many US dog owners are now more price-conscious and value-driven. They scrutinise their spending more closely, set priorities, and distinguish more clearly between necessary purchases and non-essential extras.
For the pet market, this means that not every product category benefits equally from the growth in dog ownership. The added value that a product or service offers to both pet and owner is becoming increasingly important.
Basic needs remain a priority
There is clear prioritisation when it comes to spending. Basic needs, such as food, continue to be met. However, when it comes to more discretionary spending, owners are more willing to make cuts. This applies to certain products and services, as well as veterinary care in some cases.
At the same time, the definition of ‘value’ is changing. There is a growing demand for products that offer an immediately apparent benefit, such as health and safety benefits, or benefits relating to the dog’s daily care and maintenance.
Conversely, less essential purchases and products that are perceived as more optional luxuries are under increasing pressure to justify their cost. These purchases are either reduced, replaced with cheaper alternatives or postponed.
71 millon
households in the US owned dogs in 2025
Reallocation rather than cutbacks
Nevertheless, there is no indication that the number of people owning dogs is generally declining. In fact, the report’s findings suggest that current behaviour can be described as a reallocation of spending.
Owners remain committed to their pets but are paying closer attention to how they allocate their budget. Therefore, the key question for the industry is not so much whether dog owners are spending money, but what they are spending it on and what value they expect in return.
This is of particular interest to retailers. According to the APPA survey, retailers who combine competitive prices with convenience are particularly attractive. Value for money and ease of availability are thus becoming increasingly important.
In turn, the pressure is mounting on manufacturers to clearly communicate the specific benefits of their products. Functionality, durability, health benefits and ease of use can be key selling points.
This shift in perception of value is also reflected in product preferences. Despite having tighter budgets for discretionary spending, dog owners continue to opt for products related to interaction, preventive care, and daily grooming.
They rely on a mix of different forms of care for this: products for daily needs at home are supplemented by support from family and friends, as well as professional services when more specialised care is required.
This presents opportunities for suppliers, particularly those offering products and services that provide clear functional added value while also catering to price-conscious consumer behaviour.
Not a generational issue
The APPA Report reveals interesting generational trends in pet ownership. In recent years, younger generations have had a significant influence on pet ownership and have introduced new perspectives on why, when and how households take on a pet.
However, in 2025, it became apparent that the growth in dog ownership was taking place across all generations.
The proportion of Generation Z dog owners rose from 20 to 21 per cent between 2024 and 2025 – an increase of 5 per cent year on year. Generation X saw an even stronger rise, with their share increasing from 25 to 28 per cent – a growth of 12 per cent.
Dog ownership is therefore continuing to grow in popularity amongst both younger and middle-aged generations. Consequently, it is becoming increasingly important for the industry to consider different life situations and consumer needs, rather than defining the dog market based solely on the behaviour of younger target groups.
The latest comprehensive APPA data set on dog ownership is available to purchase from the online shop at




 Newsletter